Singapore Asset Recovery: Why Seizing a Luxury Property Is Only Half the Job
Singapore asset recovery has entered a less dramatic but equally important stage following the country’s S$3 billion money-laundering case: converting forfeited luxury property into actual recoverable value.
Seizing or forfeiting an expensive asset can look like the end of an investigation.
In reality, it may only be the beginning of the recovery process.
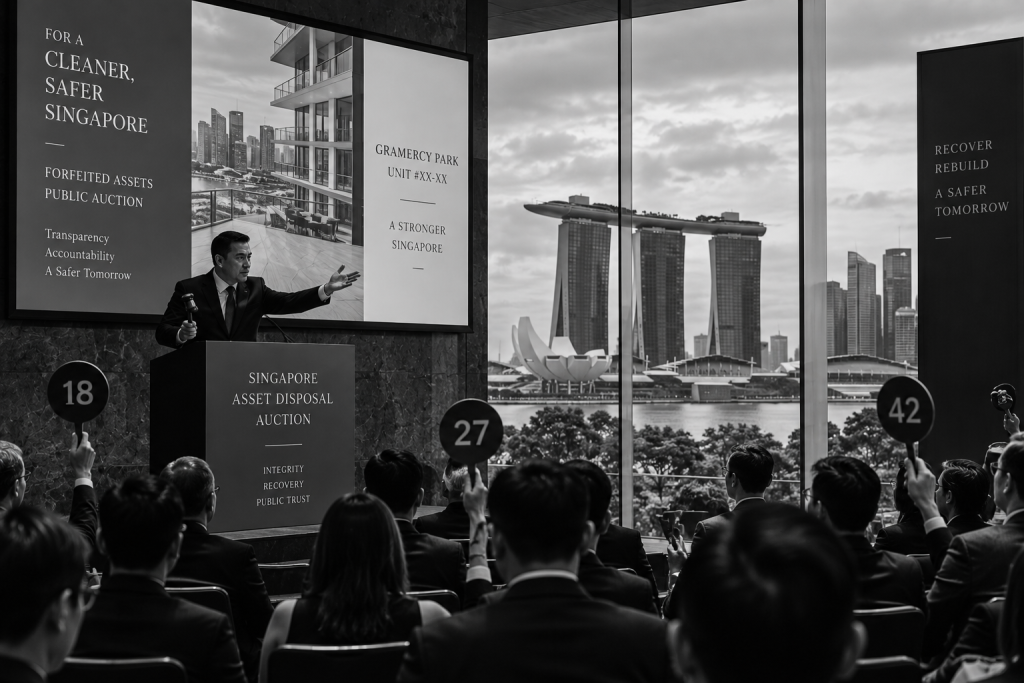
On 17 September 2026, the first seven forfeited properties from Singapore’s high-profile money-laundering case were offered at auction by Knight Frank. The room attracted significant attention, with 65 people present and 30 bidders pre-registered, but none of the seven properties completed a sale.
The properties included four units at Gramercy Park, two at Sloane Residences and a Grade A office at Suntec Tower 1. Some units received no bids, while others attracted offers that did not reach their reserve prices and were withdrawn.
That result should not automatically be interpreted as evidence that the assets were overvalued.
Knight Frank told CNA that withdrawals are not unusual at property auctions, while the actual reserve prices were not publicly disclosed. The auction house said it would seek instructions on whether to negotiate privately with bidders or repeat the auction process.
The more useful lesson is broader:
An asset can appear highly valuable on paper while still being difficult, expensive or time-consuming to convert into recoverable cash.
That is the central challenge in asset realisation.
From S$3 Billion Seizure to Singapore Asset Recovery
The September property auctions form part of the continuing disposal of assets connected with Singapore’s largest money-laundering case.
More than 80 forfeited properties are expected to be marketed between September 2026 and mid-2027. CNA reported that the property portfolio includes luxury residential units, commercial property and other real estate connected to assets forfeited after the 2023 investigation.
Singapore has already been progressively liquidating assets connected with the case.
The Ministry of Home Affairs reported that, as of December 2024, approximately S$2.79 billion in assets had been surrendered to the state. Of that amount, around S$1.54 billion consisted of cash or financial assets, while the remainder included properties, vehicles and luxury goods.
This distinction between cash and non-cash assets matters.
Cash is already liquid.
A condominium, office, vehicle, watch or other physical asset has to be maintained, valued, marketed and sold before its value can be realised.
That creates what can be thought of as a recoverability gap:
Estimated asset value ≠ immediately recoverable value.
For law firms and companies dealing with disputes, fraud or enforcement matters, this is why asset discovery and tracing should consider not only whether an asset exists, but whether it can realistically be converted into value.
What Happened at the First Property Auction?
The seven forfeited properties offered on 17 September included:
- Four Gramercy Park apartments
- Two Sloane Residences apartments
- One office unit at Suntec Tower 1
Guide prices ranged from approximately S$3.6 million for some residential units to S$11.5 million for the Suntec office.
Several properties attracted no bids.
Others did attract competition.
One Gramercy Park unit, for example, reached S$6.7 million before being withdrawn because the bid did not meet the reserve price. Another drew bidding up to S$3.75 million but was also withdrawn. The Suntec office received a counter-offer of S$8 million against an opening level of S$11 million and was likewise withdrawn.
This illustrates one of the fundamental differences between valuation and realisation.
A property may have:
- An indicative valuation
- A guide price
- A reserve price
- A market asking price
- A bid price
- A final transaction price
Those figures can all be different.
For an asset-recovery strategy, the number that ultimately matters is the net amount that can actually be realised.
The Recoverability Discount
A luxury apartment may be worth several million dollars according to comparable sales.
But that does not mean a buyer will immediately pay that amount.
The difference between theoretical value and practical recoverability can arise from several factors.
1. Reserve Price
A seller may be unwilling or unable to accept offers below a specified threshold.
At auction, this means a property can attract genuine buyer interest while still remaining unsold.
That appears to have occurred with several of the forfeited Singapore properties.
This does not necessarily mean the bidder’s offer represents the property’s objective market value.
It simply shows that the buyer’s price and seller’s required price did not meet.
2. Property Condition
The physical condition of an asset directly affects recoverability.
A prospective bidder cited by CNA said one Sloane Residences property could require substantial renovation, estimating at least S$200,000 in work after inspecting the unit.
For an asset-recovery investigation, this is an important reminder:
Gross asset value is not the same as net recoverable value.
Potential costs can include:
- Repairs
- Renovation
- Maintenance
- Property management
- Taxes
- Professional fees
- Auction fees
- Legal expenses
- Financing costs
A property worth S$5 million in principle may generate materially less once those considerations are taken into account.
3. Marketability
Some assets have a very deep buyer market.
Others do not.
A standard apartment in a highly liquid market may attract many purchasers.
An unusually large luxury unit, niche commercial property, specialised industrial asset or highly customised residence may have a much smaller pool of potential buyers.
This matters during forced or structured disposal.
The theoretical value of an asset is only useful if someone is willing and able to buy it.
4. Financing
High-value property often depends on financing.
Potential buyers may need time for:
- Bank approval
- Loan-to-value assessment
- Valuation
- Due diligence
- Internal investment approval
Auction processes can require deposits and completion within specified periods. CNA reported that successful bidders in the 17 September auction would have been expected to place a deposit and complete the transaction within about 10 weeks.
A compressed timetable can reduce the practical buyer pool.
5. Ownership and Encumbrances
Before pursuing any asset, investigators should establish more than its headline value.
Questions may include:
Who legally owns it?
Is the title clear?
Is it mortgaged?
Are there third-party interests?
Is it subject to litigation?
Is someone occupying it?
Are there restrictions affecting transfer?
Is another jurisdiction involved?
Compliancia’s asset discovery investigations examine property, corporate ownership, international assets and other financial interests to help legal teams understand what may actually be recoverable.
Asset Preservation Also Costs Money
Assets do not simply sit still while legal proceedings continue.
They cost money to preserve.
Singapore’s Ministry of Home Affairs previously reported costs associated with storing, maintaining and safeguarding properties, vehicles and luxury goods seized in the 2023 case. The government said approximately S$646,000 had been incurred by March 2024 for the management and preservation of seized assets.
The same principle applies in private litigation.
A vehicle depreciates.
A building requires maintenance.
A business can lose customers.
A vessel needs storage.
A luxury item may require specialist conservation.
Asset recovery therefore involves a race between preservation and depreciation.
Singapore’s National Asset Recovery Strategy explicitly recognises this issue. It provides for the management and disposal of assets, including the sale of forfeited non-cash criminal assets through auction, with proceeds ultimately transferred to the Consolidated Fund.
Asset Discovery Is Different From Asset Recovery
This distinction is especially important for lawyers and clients.
An investigator may establish that a subject owns:
- A condominium
- Land
- Vehicles
- Shares
- Companies
- Bank accounts
- Luxury assets
- Offshore interests
That is asset discovery.
Recovery is the next problem.
The legal team must then determine whether those assets can be restrained, seized, enforced against or otherwise realised.
That can depend on:
- Ownership
- Jurisdiction
- Priority of claims
- Existing security
- Court orders
- Insolvency
- Nominees
- Beneficial ownership
- Local enforcement rules
The investigator’s role is therefore often to answer:
What exists? Who controls it? Where is it? What is it worth? And how recoverable does it appear to be?
Compliancia’s asset discovery services support law firms, companies and private clients seeking a clearer understanding of assets before committing to litigation or recovery action.
Why Beneficial Ownership Matters
A property search may show a registered owner.
That does not always reveal the full economic picture.
Assets can sit behind:
- Companies
- Nominee shareholders
- Trust arrangements
- Family members
- Related entities
- Offshore structures
- Intermediaries
Investigators may therefore need to map the relationship between the asset and the person who ultimately controls or benefits from it.
This is particularly relevant in cross-border matters.
A person may live in one jurisdiction, hold a company in another and own real estate through a corporate structure somewhere else entirely.
Compliancia’s broader investigation services include corporate mapping, UBO and nominee detection, fraud investigations and international asset enquiries.
Value on Paper Can Create False Confidence
One of the most common errors in recovery planning is assuming that a list of high-value assets guarantees a successful economic outcome.
Consider a hypothetical target with:
- S$8 million property
- S$2 million in vehicles
- S$1 million in company shares
At first glance, the target appears to hold S$11 million.
But investigation may later establish:
- The property has a large mortgage.
- The cars are financed.
- The company shares are illiquid.
- Another creditor has priority.
- The property requires significant renovation.
- The owner disputes beneficial ownership.
- Enforcement would require proceedings in several jurisdictions.
The headline figure remains S$11 million.
The recoverable value may be substantially lower.
This is why Compliancia’s approach to company due diligence and asset investigations goes beyond simply locating names in registries.
The objective is to understand the reality behind the asset.
Buyer Due Diligence Still Matters
For purchasers, forfeited or auctioned assets can also present opportunities.
But the existence of an official sale does not eliminate the need for due diligence.
Potential purchasers still need to understand:
- Title
- Property condition
- Financing
- Taxes
- Transaction costs
- Restrictions
- Occupancy
- Market comparables
- Exit prospects
Singapore’s anti-money-laundering framework also places importance on risk-proportionate due diligence in property transactions. In July 2026, the Urban Redevelopment Authority reminded developers that customer due-diligence and screening measures should reflect the nature, complexity and risk profile of property transactions.
For larger transactions, understanding the buyer, seller and source of funds can therefore form part of the risk analysis.
Singapore’s Broader Asset Recovery Strategy
The September auctions are part of a wider policy framework rather than an isolated disposal exercise.
Singapore’s National Asset Recovery Strategy identifies four broad objectives:
- Detect criminal and suspicious activity
- Deprive criminals of illicit proceeds
- Maximise recovery for forfeiture or victim restitution
- Deter the use of Singapore for hiding or moving illicit assets
The government has said that asset recovery is a key component of its anti-money-laundering system, particularly because many cases have transnational characteristics.
That third objective — maximum recovery — is particularly relevant to the current property auctions.
Seizure removes control.
Forfeiture establishes the state’s claim.
But sale converts the asset into usable value.
All three stages matter.
What Investigators Should Test Before Recovery Action
For lawyers considering recovery proceedings, investigators should ideally test several questions before substantial legal costs are incurred.
Does the asset actually exist?
Verify the property, account, vehicle or company.
Who owns it?
Establish both legal and beneficial ownership.
What is it worth?
Use realistic rather than purely aspirational valuation assumptions.
Is it encumbered?
Check mortgages, security interests, litigation and third-party claims.
Can it be transferred?
Identify legal or practical restrictions.
Is there a buyer market?
A high valuation means little if the asset is exceptionally difficult to sell.
What will recovery cost?
Consider legal fees, investigators, valuation, preservation, taxes and enforcement.
What is the likely net result?
The ultimate question is not:
How much is the asset worth?
It is:
How much value could realistically be recovered after time, cost and risk?
Supporting Asset Recovery Across Southeast Asia
Compliancia supports law firms, companies and their counsel with asset and investigative intelligence across Southeast Asia.
Relevant capabilities include:
- Asset discovery and tracing
- Corporate ownership research
- UBO and nominee identification
- Property investigations
- International asset enquiries
- Fraud investigations
- Source enquiries
- Company due diligence
- Litigation support
- Counterparty intelligence
- On-the-ground verification
Our objective is not simply to locate an asset.
It is to help answer the more commercially important questions:
Who owns it?
Who controls it?
What is it realistically worth?
What liabilities sit against it?
Can it be enforced against?
And is recovery economically worthwhile?
Learn more about Compliancia’s asset discovery capabilities or our broader investigation and litigation-support services.
Editorial Note
This article discusses the disposal of assets forfeited in connection with Singapore’s S$3 billion money-laundering case.
On 17 September 2026, none of the first seven forfeited properties offered at auction completed a sale. That result should not be interpreted as evidence that the properties were improperly valued or that forfeited properties generally trade at a discount.
According to CNA’s reporting, some properties attracted no bids while offers for others did not reach undisclosed reserve prices. Auction specialists interviewed by CNA noted that withdrawals from property auctions are not unusual.
The term “recoverability discount” in this article is used as an analytical concept to describe the possible difference between an asset’s nominal or estimated value and the net amount ultimately realisable after market, financing, condition, legal, maintenance and transaction factors are considered. It does not represent a calculated discount attributed to these Singapore properties.